
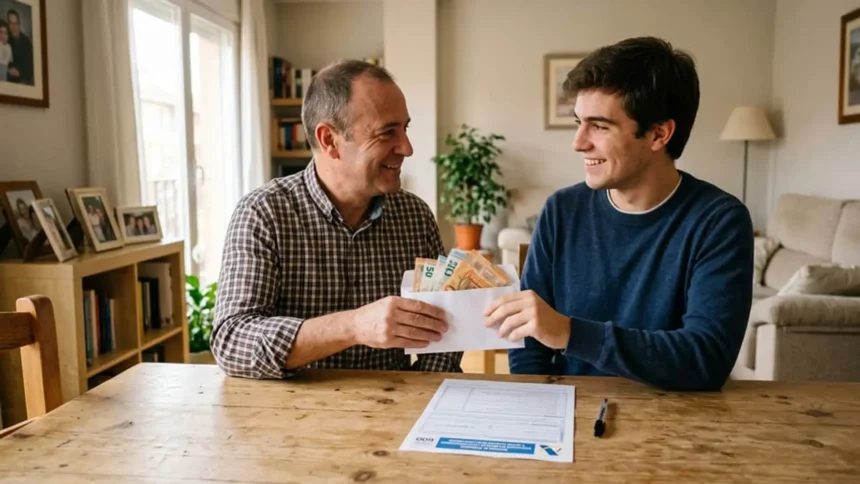
Giving children an inheritance while they are between 26 and 35 could allow them to use the money during a period of greater financial need, rather than receiving it after many of their major expenses have already been covered.
That is the argument made by entrepreneur and author Bill Perkins, who says parents should first calculate how much wealth they need for retirement, medical care and other future expenses before transferring any excess to their children.
Perkins, author of Die With Zero, challenges the traditional approach of accumulating wealth throughout life and passing it on after death. He argues that the value of an inheritance depends not only on how much money is given, but also on when the recipient can use it.
According to Perkins, ages 26 to 35 can be a particularly important period, when people may be buying their first home, starting families and building their careers.
An early inheritance could also help reduce debt. A larger down payment on a home, for example, could lower the mortgage balance, future interest costs or the need for private mortgage insurance. The money could also be used for student loans, child care, medical expenses or starting a business.
More Read
However, giving away money too early can create financial risks for parents. They should account for retirement savings, emergency expenses, medical care and the possibility of needing long-term care before transferring assets.
Tax considerations
In 2026, the federal annual gift-tax exclusion is $19,000 per recipient. A married couple could potentially give a child $38,000 if each spouse makes a separate gift.
Giving more than the annual exclusion does not necessarily mean the donor immediately owes gift tax. The excess generally counts against the donor’s lifetime federal gift and estate tax exemption, which the source identifies as $15 million per person in 2026, but a gift-tax return may be required.
Cash is generally simpler to transfer than appreciated property such as stocks or a home. A recipient who receives an appreciated asset during the donor’s lifetime may inherit the donor’s original tax basis, potentially resulting in a larger capital-gains tax bill when the asset is sold.
By contrast, inherited property can receive a tax basis adjustment based on its value at the owner’s death, which can make the tax consequences of gifting property during life different from leaving it as an inheritance.
Families should also consider potential Medicaid consequences. Certain transfers made within the five-year look-back period can affect eligibility for institutional long-term-care coverage.
How to approach an early inheritance
Before transferring money, families should determine how much they can afford to give without compromising their own financial security. The source recommends considering retirement costs, inflation, insurance, medical care and the possibility of a longer-than-expected retirement.
Families can also document whether the transfer is a gift or a loan, keep records of the amount and date, file Form 709 when required and consult a tax professional before transferring property or investments.
Perkins’ proposal does not establish a universal age for receiving an inheritance. Rather, it argues that transferring wealth earlier can allow recipients to use it during years when it may have a greater practical impact, provided the parents can afford the transfer.